Home Equity Investment Exchange Rates: Multipliers Explained & Real Examples
The Scout Executive Summary
- The exchange rate sets the company’s share, not a yearly cost. Multiply your cash percentage by the rate: 10% at 2x means the company collects 20% of your home’s value when you settle.
- The same rate can cost very different amounts. What the share applies to (your full home value or only the gain), the starting value, fees, the cap, and timing matter as much as the rate.
- Compare offers in dollars, not rates. Get quotes for the same cash amount, then ask what you’d pay at 3, 5, and 10 years if your home’s value rises, stays flat, or drops.
In This Article:
- What Is an HEI Exchange Rate?
- How Do You Use an Exchange Rate to Find the Company’s Share?
- What Exchange Rates Do HEI Companies Use?
- Does a Lower Exchange Rate Mean a Cheaper HEI?
- What Happens to the Company’s Share If Your Home Loses Value?
- How Do You Compare HEI Offers Before You Sign?
- HEI Exchange Rate: Common Questions
An HEI exchange rate is the multiplier that turns the cash you take from a home equity investment (HEI) into the company’s share of your home. It is one of the first numbers you will see on an offer, and one of the easiest to misread.
This guide shows how to use it, what real rates look like, and why the lowest rate is not always the cheapest deal.
What Is an HEI Exchange Rate?
An HEI exchange rate is the number a company multiplies your cash by to set its share of your home.
Say your home is worth $500,000 and you take $50,000 in cash. That is 10% of your home’s value. With a 2x exchange rate, the company’s share becomes 20%. When you settle the agreement later, by selling, refinancing, buying it out, or reaching the end of the term, the company collects based on that 20%.
The exchange rate is not an interest rate. A 2x rate does not mean 2% a year, and there is no yearly charge built into it. Your final cost depends on what your home is worth when you settle and how long you keep the agreement. To see how that compares with a product that has a set interest rate, read our HEI vs. HELOC cost comparison.
Companies do not all use the same name for it. Nada calls it an exchange rate. Hometap calls it a multiplier. Others show you only the final share.
How Do You Use an Exchange Rate to Find the Company’s Share?
To find the company’s share, divide your cash by your home’s starting value, then multiply that percentage by the exchange rate.
Curious if an HEI makes sense for your situation? You can pre-qualify in minutes without impact to your credit. Check Your Eligibility with Point →
The Formula
Example: $50,000 ÷ $500,000 = 10%, and 10% × 2 = 20%
Using the same numbers, $50,000 is 10% of a $500,000 home. Ten percent times 2 is 20%. The Consumer Financial Protection Bureau (CFPB) uses this same example: cash equal to 10% of the home’s value in exchange for a 20% share.
| Example Input | Amount |
|---|---|
| Home’s starting value | $500,000 |
| Cash you receive (before fees) | $50,000 |
| Share of your home value | 10% |
| Exchange rate | 2x |
| Company’s share | 20% |
Two inputs trip people up. First, fees are taken out of the cash you receive, so ask which amount the company used to set your share. Second, check the starting value. Some companies start the math from a value lower than your appraisal, which changes the result.
You can also run the math backward to check an offer. If an offer shows a 20% share on 10% cash, divide 20 by 10 to get the exchange rate: 2x. If the numbers do not match what you were told, ask why before you sign. How much cash you can take in the first place depends on your HEI equity requirements.
Scout’s Tip
Before you compare offers, ask each company to put four numbers on one page: the cash amount before fees, the starting home value it used, the exchange rate, and whether the share applies to your home’s full value or only the gain. Nada and Hometap publish their multipliers, which make useful benchmarks when another offer shows you only a share.
What Exchange Rates Do HEI Companies Use?
A few HEI companies publish their exchange rates, but many show your number only in a written offer. Either way, the number that counts is the one in your contract.
Enjoy no monthly payments for up to 30 years with a Point Home Equity Investment. See If You Prequalify →
Nada’s pricing page says its standard exchange rate starts at 1.85. On cash equal to 10% of your home’s value, that is an 18.5% share, which Nada applies to your home’s appraised value when you settle. “Starts at” means your rate can be higher, so confirm it on your own offer.
Hometap ties its multiplier to timing. Its June 2026 pricing announcement says homeowners who settle within the first five years get a 1.65x multiplier, and those who settle after year five get 1.80x. Hometap applies its share to your home’s market value when you settle.
Point Home Equity Investment (HEI)

Get cash from your home equity in exchange for a share of your home’s future value.
- PaymentsNo monthly payments
- TermUp to 30 years to settle
- CreditCredit scores starting at ~600+
- IncomeNo income requirements
- Cash availableAccess up to $600,000
Other companies do not publish a ratio. Point, for example, says your share depends on factors like your credit, the amount you request, and your property, and it shows the exact percentage only in your offer.
Here is how those rates move the company’s share when you take 10% in cash and your home is worth $600,000 at settlement:
| Exchange Rate | Company’s Share | Share of a $600,000 Home |
|---|---|---|
| 1.65x (Hometap, settle within 5 years) | 16.5% | $99,000 |
| 1.80x (Hometap, settle after year 5) | 18% | $108,000 |
| 1.85x (Nada’s starting rate) | 18.5% | $111,000 |
| 2x (CFPB example) | 20% | $120,000 |
These are simple examples before any cap, fees, or other contract terms. Each company’s contract sets its own formula.
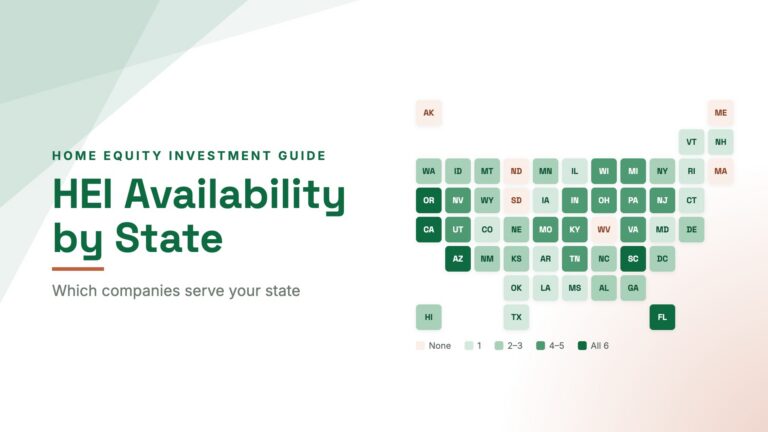
Which companies you can use also depends on where you live. If you are in Arizona, our guide to HEI companies in Arizona compares the providers working here.
Does a Lower Exchange Rate Mean a Cheaper HEI?
No. A lower exchange rate means a smaller share only when everything else about two offers is the same, and it rarely is. Three other terms can move your cost as much as the rate does.
Keep your existing low mortgage rate while accessing cash upfront with Point. Explore Point Eligibility →
What the Share Applies To
Some companies apply their share to your home’s full value when you settle. Others apply it only to the gain since you signed. The CFPB notes this difference makes offers hard to compare. Here is the same 20% share on a $500,000 home that grows to $600,000:
| If the 20% Applies To | Company’s Share |
|---|---|
| Your home’s full value | $120,000 |
| Only the $100,000 gain | $20,000 |
Gain-based agreements may also return your original cash or use a higher percentage, so the real gap can be smaller. The point is that the same 20% can mean very different money.
The Starting Value
Some companies start the math from a home value lower than your appraisal. The CFPB gives an example of a starting value set 25% below the appraised value. On a $500,000 home, that is a $375,000 starting point. In a gain-based agreement, if your home is still worth $500,000 when you settle, the contract counts $125,000 of gain even though your home’s price never moved.
Fees, Caps, and Timing
Fees come out of your cash up front. A safety cap limits the most the company can collect, which matters most if your home’s value jumps. Because your cost depends on your home’s value over time, when you settle and what happens if your home value drops both change the final number. Some companies also credit you for qualifying improvements.
The better deal still depends on the written offers, including the funding amount, starting value, fees, settlement formula, and timing of the buyout.
Scout’s Tip
If you would rather compare costs as one interest rate, a HELOC gives you that. Check current Arizona HELOC and home equity rates before you decide an HEI is the better fit.
What Happens to the Company’s Share If Your Home Loses Value?
The exchange rate and the share percentage stay the same, but the dollar amount the company collects falls along with your home’s value.
Want to access your home equity without monthly payments? Check your pre-qualification with Point in just a few minutes. Get Your Estimate →
Take the same example: 10% cash at 2x, for a 20% share applied to your home’s full value. If your $500,000 home is worth less when you settle, the company’s 20% is worth less too:
| Home Value at Settlement | Company’s 20% Share |
|---|---|
| $500,000 (no change) | $100,000 |
| $400,000 | $80,000 |
| $300,000 | $60,000 |
| $250,000 | $50,000 |
The company still collects more than the $50,000 it paid you until your home loses half its value. The CFPB makes the same point: at 2x, a home would have to drop more than 50% before the company loses money.
Other contract terms change this picture. With a lower starting value, a small drop can still count as a gain on paper. In a gain-based agreement, ask what you pay if there is no gain and whether there is any minimum amount due. For more scenarios, see what happens to an HEI if your home value drops.
How Do You Compare HEI Offers Before You Sign?
Compare HEI offers in dollars, not exchange rates. Use these three steps with every offer you get.
Curious if an HEI makes sense for your situation? You can pre-qualify in minutes without impact to your credit. Check Your Eligibility with Point →
Before You Sign: Compare Offers in 3 Steps
- Line up the same inputs. Request the same cash amount from each company. Then get the cash you would receive after fees, the starting home value next to your appraisal, the exchange rate, and the resulting share.
- Check what the share applies to and what limits it. Confirm whether the share applies to your full home value or only the gain, plus the cap, any minimum amount due, the term length, and any credit for improvements.
- Ask for dollar estimates at 3, 5, and 10 years. Have each company show what you would pay at settlement if your home value rises, stays flat, or drops. Comparing those totals side by side tells you more than the rate alone.
If one offer looks better on a single term, it is fair to ask the other company whether it can match it.
Featured Partners · No Monthly Payments
- Up to 30 years to settle
- Credit scores starting at ~600+
- Access up to $600,000

Home Equity Agreement (HEA)
- Use cash for anything
- 500+ credit score. No income requirements.
- Pre-qualify in under 2 minutes. No credit impact.

- Qualify in minutes. No credit impact.
- Close in as little as 3 weeks1
- Works for second homes and rentals

- Qualify in minutes
- Dedicated Investment Manager
- Access up to $600,000

- Up to 30 years to settle with MaturityMatch™
- Keep your low-rate mortgage
- Check eligibility with no credit impact
Unlock: In exchange for cash upfront, you give a share of the future value of your home. Not all homeowners will qualify. Not available in all states. Terms and conditions apply. Home Equity Agreements offered by Unlock Home Equity Solutions Inc. (NMLS #2657081).
Nada: 1“Close in as little as 3 weeks” reflects the average timeline under standard conditions. Actual timelines vary based on documentation, title, property location, and local recording or notarization requirements. Timing is not guaranteed. Terms and conditions apply. Not all homeowners will qualify. Not available in all states. Nada Loans LLC, NMLS #1993600.
HEI Exchange Rate: Common Questions
No. A 2x exchange rate means the company’s share of your home is twice the percentage you took in cash. There is no yearly rate built into it. What you end up paying depends on your home’s value when you settle and the terms in your contract.
Yes. The share is your cash percentage times the exchange rate, so more cash means a bigger share. Taking 5% of your home’s value at 2x gives a 10% share. Taking 10% at 2x gives a 20% share. A company may also quote a different rate at different amounts, so check the rate on each offer.
It depends on the contract. Some companies apply the share to your home’s full value when you settle. Others apply it to the increase in value since you signed. Ask which one your offer uses, because the same percentage can mean very different dollar amounts.
No. A lower rate gives a smaller share only when everything else is equal. A lower starting value, higher fees, or a share applied to your full home value can make a lower-rate offer cost more.
Ask for the exchange rate, the cash amount before fees, the starting home value, what the share applies to, the cap, and an example of what you would pay at settlement after 3, 5, and 10 years. Get the answers in writing.
Before you sign anything, weigh the pros and cons of a home equity investment and work through our questions to ask before a home equity investment.
EquitySquirrel is an educational resource operated by Scout Media LLC, not a lender or HEI provider. This content does not constitute financial, legal, or investment advice. HEI terms vary by provider and are subject to change; confirm current terms directly. Consult a licensed financial professional before making decisions about your home equity. Aleksandra Kadzielawski, Lic #SA694336000.