Which HEI Company Funds Fastest? 2026 Speed Comparison
The Scout Executive Summary
- Plan on about three weeks, not ten days. Several providers say they can fund in “as little as” two to three weeks. Those are best-case figures, not guarantees or averages. If you need the money within days, an HEI probably isn’t the right tool.
- How your home gets valued matters more than which brand you pick. An in-person appraisal is usually the slowest step. Some providers use automated or hybrid valuations instead, so ask each one which method it will use for your home before you apply.
- You control most of the delays. Gather your mortgage statement, insurance, tax records and ID before you apply. Answer every request the same day. Confirm the provider works in your state before you start.
In This Article:
- Which HEI Company Funds the Fastest?
- What Does the HEI Funding Timeline Actually Look Like?
- Why Can the HEI Appraisal Slow Funding?
- How Can You Speed Up Your Own HEI Funding?
- Is an HEI Faster Than a HELOC or Cash-Out Refinance?
- Why HEIs Skip Income Verification
- Is an HEI Fast Enough for a True Emergency?
- Which Fast HEI Provider Should You Start With?
- HEI Provider Reviews & Side-by-Side Comparisons
- Fastest HEI Funding: Common Questions
Which HEI Company Funds the Fastest?
Published information doesn’t identify a single fastest provider. Nada can fund in as little as three weeks, according to internal Nada documentation reviewed by EquitySquirrel. Unison says funding can take “as little as 10 days” for its Equity Sharing Agreement, assuming closing with its remote online notary. Unlock says the full process for its home equity agreement “typically takes 30–60 days from application to closing,” which is a typical range rather than a best case. Splitero’s FAQ says many homeowners go from application to funding “in as little as 20 days” and that timelines vary by property, while the description of its ‘How it works’ page says “as little as 10 days” (it doesn’t say whether those are calendar or business days). Hometap says “Funding in as little as 3 weeks” and that the process “can take as little as 30-45 days.” Point says approved homeowners “can close in as little as three weeks.”
See Your Timeline: Nada can fund in as little as three weeks, according to internal documentation reviewed by EquitySquirrel. Want to know how fast your equity could be funded? Nada checks your baseline eligibility with a soft credit inquiry and says its valuations use “3rd party automated tools”. [ Check Your Eligibility with Nada → ]
The table below compares provider-stated timelines from public websites and, for Nada, internal documentation reviewed by EquitySquirrel. Most are best-case figures; Unlock publishes a typical range instead. None are guarantees, and the stated starting and ending points differ.
HEI Funding Speed by Provider (2026)
| Provider | Pre-Approval Speed | Provider-stated speed (start → end) | Notes |
|---|---|---|---|
| Nada | Soft-inquiry eligibility check | As little as 3 weeks To funding, according to internal Nada documentation reviewed by EquitySquirrel; not guaranteed. | Nada says valuations use “3rd party automated tools” |
| Splitero | Estimate “in less than 2 minutes” | As little as 10–20 days Splitero’s FAQ: many homeowners go “from application to funding in as little as 20 days”; timelines vary by property. Its ‘How it works’ page description says “as little as 10 days.” Not guaranteed (application → funding; day basis not stated; checked Oct 16, 2026) | Automated valuation model in many straightforward cases; hybrid appraisal for more complex properties (per Splitero) |
| Unlock | Pre-qualify in as little as two minutes; no credit impact | 30–60 days (typical) Unlock’s FAQ: the full process “typically takes 30–60 days from application to closing.” This is a typical range, not a best case; timelines vary with appraisal scheduling, title review and documentation. | Soft credit inquiry at every stage; online valuation for some homes. Cash typically sent to escrow on the fourth business day after a three-business-day right-to-cancel period (Unlock) |
| Hometap | Prequalify in less than 2 minutes | As little as 3 weeks “Funding in as little as 3 weeks” (start and end points not stated); the entire process “can take as little as 30-45 days” | Funds typically wired “within four to seven business days of signing” (Hometap) |
| Point | Soft-inquiry estimate | As little as 3 weeks “Once approved, homeowners can close in as little as three weeks” (approval → closing) | Disbursement timing not published |
| Unison | Instant online estimate | As little as 10 days “Funding in as little as 10 days” for its Equity Sharing Agreement, assuming closing with Unison’s remote online notary; may take longer where an in-person closing or waiting period applies (start point not stated) | Estimate in seconds, then full underwriting |
Check Your Nada Eligibility. Access up to $600,000* of your home equity with no monthly payments and no minimum income requirement. Nada works with credit scores from 500 and says its valuations use “3rd party automated tools”. [ Check Your Eligibility with Nada → ]
*Terms and conditions apply. Not all homeowners will qualify. Not available in all states. NMLS #1993600, www.nmlsconsumeraccess.org. See nada.co for complete details.
For background on how home equity investments work, see the Consumer Financial Protection Bureau’s explainer.
For the full provider comparison including fees, limits, and Arizona availability, see the Top HEI Companies in Arizona guide.
Scout’s Tip
Fast estimate or fast funding? The advertised pre-approval time and the time to actual funding are two different numbers. Even a quick estimate is followed by valuation, title review and closing. When a provider advertises speed, confirm whether they mean the estimate, the approval, or money in your account.
Featured Partners · No Monthly Payments

- Up to 30 years to settle
- Credit scores starting at ~600+
- Access up to $600,000

Home Equity Agreement (HEA)
- Use cash for anything
- 500+ credit score. No income requirements.
- Pre-qualify in under 2 minutes. No credit impact.

- Qualify in minutes. No credit impact.
- Close in as little as 3 weeks1
- Works for second homes and rentals

- Qualify in minutes
- Dedicated Investment Manager
- Access up to $600,000

- Up to 30 years to settle with MaturityMatch™
- Keep your low-rate mortgage
- Check eligibility with no credit impact
Unlock: In exchange for cash upfront, you give a share of the future value of your home. Not all homeowners will qualify. Not available in all states. Terms and conditions apply. Home Equity Agreements offered by Unlock Home Equity Solutions Inc. (NMLS #2657081).
Nada: 1“Close in as little as 3 weeks” reflects the average timeline under standard conditions. Actual timelines vary based on documentation, title, property location, and local recording or notarization requirements. Timing is not guaranteed. Terms and conditions apply. Not all homeowners will qualify. Not available in all states. Nada Loans LLC, NMLS #1993600.
What Does the HEI Funding Timeline Actually Look Like?
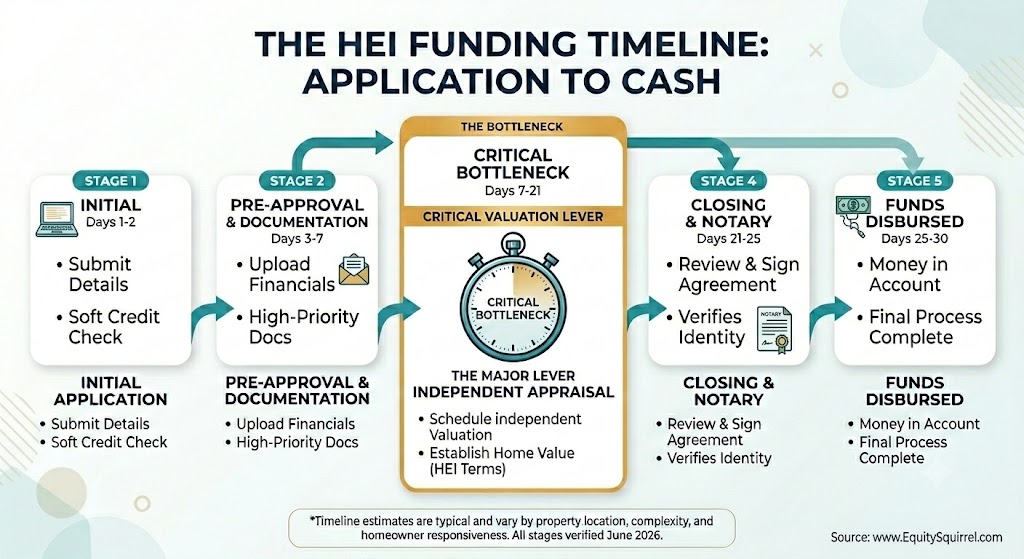
An HEI funding process generally runs through four stages: a preliminary estimate, a full application, a home valuation, and closing with funding.
Skip the Appraisal Wait: Nada says its valuations use “3rd party automated tools,” and automated valuations can shorten Stage 3. Request your eligibility check to start your property profile. [ Get Started with Nada → ]
Here is what each HEI application stage involves:
Stage 1: Preliminary estimate. You enter your address and basic information and receive a ballpark figure, usually after a soft credit inquiry with no score impact.
Stage 2: Full application and underwriting. You complete the full application, the provider pulls credit, and they order third-party reports. This is where responsiveness matters most.
Stage 3: Home valuation. The provider sets your home’s current value, which becomes the starting point for the agreement. Depending on the provider and property, that can mean an in-person appraisal or an automated or hybrid valuation.
Stage 4: Closing and funding. Closing often happens with a mobile notary, and funds are typically wired shortly after. This stage is usually quick once the appraisal is complete.
Why Can the HEI Appraisal Slow Funding?
When a provider requires an in-person appraisal, the Home Equity Investment (HEI) valuation can slow the funding process, because it depends on the appraiser’s availability, the inspection and the report turnaround. Because an HEI is tied to your home’s value at the start and at settlement, the provider must set a starting value before closing.
The Three Primary Appraisal Bottlenecks
- Local Market Density and Demand: When an in-person appraisal is required, the visit depends on appraiser availability in your area, and busy periods can push appointments out.
- Valuation Method: Valuation methods vary. Splitero says it can use an automated valuation model in many straightforward cases and may order a hybrid appraisal for more complex properties; Point uses “a licensed and independent appraiser or, where appropriate, … a property valuation product”; Nada says valuations use “3rd party automated tools.”
- The Written Report Turnaround: After leaving your property, the appraiser must manually analyze recent comparable sales (“comps”) within your specific zip code and compile a legally defensible valuation report.
Want to Avoid the Appraisal Queue Entirely? Nada says its valuations use “3rd party automated tools.” Nada also says it conducts a soft credit pull during the application process. [ Request Your Preliminary Property Review → ]
Scout’s Tip
Appraisal coming up? If an in-person appraisal is required, have your home ready before the appraiser arrives. Clean, accessible spaces, a list of recent improvements with rough costs, and easy access to every room can prevent a re-visit. A smooth appraisal is one of the few timeline levers you actually control.
How Can You Speed Up Your Own HEI Funding?
You can speed up your HEI funding by preparing your documents in advance, responding to requests the same day, and choosing a provider known for fast processing. The provider’s marketing sets the floor, but your responsiveness sets your real timeline.
Pre-qualify with Unlock in under 2 minutes with no impact on your credit. →
Practical steps that shorten the process:
- Gather documents before you apply. Have your mortgage statement, homeowner’s insurance, property tax records, and identification ready.
- Respond same-day to every request. The single most common cause of delay is a homeowner who takes days to return a signature or a document.
- Confirm your provider operates in Arizona before you start, so you do not lose time on an application that cannot close.
- Prepare for the appraisal so it can be completed in one visit.
- Choose a fast HEI provider if speed is genuinely your priority, rather than defaulting to the most-advertised name.
If you are weighing speed against the size of the payout, see our companion guide on which HEI company has the highest limits.
Want a second quote to compare? Unlock’s home equity agreement (HEA) is available with credit scores from 500 and has no income requirements. You can pre-qualify in under 2 minutes with no credit impact. [ Check Your Eligibility with Unlock → ]
Is an HEI Faster Than a HELOC or Cash-Out Refinance?
Published information doesn’t support a general answer. HEI providers publish best-case figures (see the table above), not averages, so there’s no reliable HEI average to compare with HELOC or cash-out refinance timelines.
Why HEIs Skip Income Verification
The fundamental reason HEIs skip traditional income verification is that an HEI is not a loan; it is an equity partnership.
See If You Qualify with Unlock →
When you apply for a traditional mortgage, HELOC, or cash-out refinance, you are taking on debt. Because these products carry mandatory monthly payments, lenders evaluate whether you can repay, generally using your debt-to-income (DTI) ratio and reviewing pay stubs, W-2s, and tax returns. For most closed-end mortgages, including cash-out refinances, federal Ability-to-Repay rules formalize this review.
An HEI completely flips this model:
- No Monthly Payments: Because there is no monthly principal or interest payment due, there is no “ability to repay” a monthly obligation to evaluate.
- Asset-Based Underwriting: Instead of underwriting you (the borrower), the HEI provider underwrites the asset (your home). The investor’s return is tied entirely to the future appreciation or depreciation of the property when you eventually settle the investment (typically via a home sale or refinancing within a 10-to-30-year term).
With a HELOC or cash-out refinance, the lender typically wants:
- Pay stubs
- W-2s
- Tax returns
- Employment verification
- Bank statements
They’re trying to determine whether you can repay a monthly loan payment. As a result, HEIs usually require less income documentation than traditional financing.
Is an HEI Fast Enough for a True Emergency?
An HEI is generally not built for a same-week emergency. No provider here guarantees a timeline. Splitero’s published timing information is inconsistent: its FAQ says ‘as little as 20 days,’ while the description of its ‘How it works’ page says ‘as little as 10 days.’ Neither is a guaranteed funding date. Confirm the expected timeline for your property directly with Splitero. If you need cash within days, an HEI is rarely the right tool.
Check Your Eligibility with Unlock →
For genuinely urgent needs, valuation, title and closing steps still take time with any provider. An HEI works best when you have a few weeks of runway, not a few days.
If your need is immediate, it is worth comparing all of your fast-access options side by side, including products that can move faster than an HEI. See the Fast Home Equity Options in Arizona guide for a full comparison.
Scout’s Tip
Working against a deadline? If you are facing a real deadline, start the appraisal step as early as possible and ask your provider directly: what is your realistic funding timeline for my Arizona property right now? A provider’s honest answer to that question is more useful than any advertised average.
Featured Partners · No Monthly Payments
- Up to 30 years to settle
- Credit scores starting at ~600+
- Access up to $600,000
Home Equity Agreement (HEA)
- Use cash for anything
- 500+ credit score. No income requirements.
- Pre-qualify in under 2 minutes. No credit impact.
- Qualify in minutes. No credit impact.
- Close in as little as 3 weeks1
- Works for second homes and rentals
- Qualify in minutes
- Dedicated Investment Manager
- Access up to $600,000
- Up to 30 years to settle with MaturityMatch™
- Keep your low-rate mortgage
- Check eligibility with no credit impact
Unlock: In exchange for cash upfront, you give a share of the future value of your home. Not all homeowners will qualify. Not available in all states. Terms and conditions apply. Home Equity Agreements offered by Unlock Home Equity Solutions Inc. (NMLS #2657081).
Nada: 1“Close in as little as 3 weeks” reflects the average timeline under standard conditions. Actual timelines vary based on documentation, title, property location, and local recording or notarization requirements. Timing is not guaranteed. Terms and conditions apply. Not all homeowners will qualify. Not available in all states. Nada Loans LLC, NMLS #1993600.
Which Fast HEI Provider Should You Start With?
Start with the provider whose eligibility fits your situation, then ask each one for a realistic timeline for your property. If you want a second offer to compare, request estimates from two providers at the same time.
Nada is one option to consider when speed matters, with funding available in as little as three weeks according to internal documentation reviewed by EquitySquirrel.
Curious whether Nada fits your situation? Check Your Eligibility with Nada →
A sensible approach when time matters:
- Confirm availability first so you do not waste days on a non-starter.
- Get a preliminary estimate from Nada and one other provider to compare both speed and offer.
- Schedule the appraisal immediately once you choose, since it is the longest step.
- Stay reachable through closing so nothing waits on you.
Before committing to any provider for speed alone, make sure an HEI is the right product for your situation. See the Home Equity Investment Guide and confirm you understand the HEI settlement obligations at term end.
In-Depth HEI Provider Reviews & Side-by-Side Comparisons
If you are weighing fast funding speeds against long-term appreciation costs, credit score minimums, or term limits, explore our full library of hands-on review guides and head-to-head match-ups before applying:
Individual HEI Lender Reviews:
- Point Review: Ideal for homeowners seeking low credit requirements (down to 500 FICO) and a long 30-year agreement runway. Read our full Point Review
- Hometap Review: Offers funding up to $600K and, per Hometap, no income requirements, balanced against a strict 10-year term limit. Read our full Hometap Review
- Unison Review: Offers 30-year terms and requires a mid-FICO score of at least 620. Read our full Unison Review
- Splitero Review: Excellent for fast pre-approvals, flexible credit underwriting (down to 500), and zero income documentation requirements. Read our full Splitero Review
- Nada Review: Offers credit minimums from 500 for primary and second homes, an annualized cost cap of 19.99% (or your state’s maximum, if lower), and the ability to unlock equity on investment properties alongside primary residences. Read our full Nada Review
Head-to-Head HEI Provider Comparisons:
- Point vs. Hometap: Compare Point’s 30-year flexibility against Hometap’s 10-year repayment deadline. Read the Point vs. Hometap Breakdown
- Splitero vs. Hometap: See how Splitero’s 30-year term and low credit barrier stack up against Hometap’s 10-year settlement window. Read the Splitero vs. Hometap Comparison
- Hometap vs. Unison: Weigh Hometap’s simpler qualifying process against Unison’s extended 30-year term and 5% risk adjustment. Read the Hometap vs. Unison Comparison
- Point vs. Splitero: Compare two HEI options that accept 500 FICO scores to see how their terms differ. Read the Point vs. Splitero Comparison
- Nada vs. Splitero: Compare Nada’s 10-year term and 19.99% annualized cost cap with Splitero’s 10-to-30-year term matched to your mortgage. Read the Nada vs. Splitero Comparison
Fastest HEI Funding: Common Questions
Published information doesn’t identify a single fastest provider. Splitero’s FAQ says many homeowners go from application to funding “in as little as 20 days” and that timelines vary by property, while its ‘How it works’ page description says “as little as 10 days” (day basis not stated); Hometap says “Funding in as little as 3 weeks” and that the process “can take as little as 30-45 days”; Point says approved homeowners “can close in as little as three weeks.” Nada can fund in as little as three weeks, according to internal Nada documentation reviewed by EquitySquirrel. This is a best-case estimate, not a guaranteed timeline. Unison says funding can take “as little as 10 days” for its Equity Sharing Agreement, assuming closing with its remote online notary. Unlock says the full process for its home equity agreement “typically takes 30–60 days from application to closing,” which is a typical range rather than a best case. Apart from Unlock’s range, all of these are best-case figures.
None of the providers compared here publishes an average. Their best-case statements include Splitero’s FAQ figure of “as little as 20 days” (application to funding; timelines vary by property; its ‘How it works’ page description says “as little as 10 days”) and Hometap’s “as little as 30-45 days” for the entire process; Hometap separately says “Funding in as little as 3 weeks.” Nada can fund in as little as three weeks, according to internal documentation reviewed by EquitySquirrel. Your timeline depends on valuation, documents, title and responsiveness.
When a provider requires an in-person appraisal, you wait for the appraiser’s availability, the inspection and the written report. Some providers use automated or hybrid valuations in many cases. Either way, an HEI can’t close until the provider has set your home’s starting value.
Yes, with some providers. Nada says its valuations use “3rd party automated tools,” and Splitero says it can use an automated valuation model in many straightforward cases. Confirm which method your provider will use before you apply, because it can affect how fast you get funded.
Usually not for a same-week emergency. No provider here guarantees a timeline. Splitero’s published timing information is inconsistent: its FAQ says ‘as little as 20 days,’ while the description of its ‘How it works’ page says ‘as little as 10 days.’ Neither is a guaranteed funding date. Confirm the expected timeline for your property directly with Splitero. If you need cash within days, compare other fast-access options rather than relying on an HEI.
Yes. Gathering your documents in advance, responding to requests the same day, and preparing your home if an appraisal visit is needed are steps you control. The provider’s own process and valuation method also affect timing.
As of October 16, 2026, these providers list Arizona on their own sites: Hometap includes Arizona among the states where it currently makes home equity investments; Point says it’s available in select regions of Arizona, and availability may vary by county; Splitero says it can help homeowners in eligible areas of Arizona; Nada lists Arizona among its eligible states; and Unison lists Arizona among the states where its equity sharing agreements are available. Eligibility requirements apply and availability can change, so confirm it for your property with each provider. This list isn’t a ranking by funding speed.
The figures compared here do not establish an average HEI funding timeline. Nada’s “as little as three weeks” funding estimate is a best-case figure, not an average. Actual timing depends on the provider, valuation, documentation, title, and applicant responsiveness.
Splitero’s published timing information is inconsistent: its FAQ says ‘as little as 20 days,’ while the description of its ‘How it works’ page says ‘as little as 10 days.’ Neither is a guaranteed funding date. Confirm the expected timeline for your property directly with Splitero. Splitero doesn’t say whether these are calendar or business days.
Credit score affects HEI eligibility and offer terms. We didn’t find a published statement from the providers compared here on how credit score affects funding speed.
No provider in this comparison publishes a comparable average time from application to funding, so this page doesn’t name a single fastest company. Here is what each provider says. Splitero’s FAQ says many homeowners go from application to funding “in as little as 20 days” and that timelines vary by property, while the description of its ‘How it works’ page says “as little as 10 days” (it doesn’t say whether those are calendar or business days). Hometap says “Funding in as little as 3 weeks” and, elsewhere on its site, that the process “can take as little as 30-45 days.” Point says approved homeowners “can close in as little as three weeks.” Nada can fund in as little as three weeks, according to internal Nada documentation reviewed by EquitySquirrel. Unison says funding can take “as little as 10 days” for its Equity Sharing Agreement, assuming closing with its remote online notary. Unlock says the full process for its home equity agreement “typically takes 30–60 days from application to closing,” which is a typical range rather than a best case. Your actual timeline depends on your valuation method, your documentation, and how quickly you respond.
EquitySquirrel, operated by Scout Media, LLC, is an educational resource, not a lender, financial advisor, or legal advisor. This content does not constitute financial, legal, or lending advice. Funding timelines are provider-stated best-case estimates drawn from public websites (checked November 12, 2026; Splitero rechecked November 12, 2026) and, for Nada, internal documentation reviewed by EquitySquirrel. Timelines are not guaranteed and vary by valuation, documentation, title, and applicant responsiveness. Provider availability varies by state. Confirm all current terms and timelines directly with each provider, and consult a licensed financial advisor before making major decisions about your home equity. Aleksandra Kadzielawski, Lic #SA694336000.