Should You Use Home Equity to Help Your Adult Child Buy a House? (2026)
Using home equity to help your child buy a house can make sense, but only if you could lose that money without hurting your retirement, your emergency savings or your ability to stay in your own home. That’s the test this guide keeps coming back to.
You’re far from alone in asking. In the National Association of Realtors’ 2026 buyer profile, 25% of first-time buyers used a gift or loan from family or friends for their down payment, and the typical first-time buyer was 40 years old. That age matters for you, too. If your child is 40, you may be in your 60s or 70s, and any debt you take on now could still be on your house when you’re in your 90s.
Below, we compare the five main ways to help, run the numbers on $75,000, explain how each choice affects your child’s mortgage, and help you decide whether it’s safe for you.
Scout Executive Summary
- Protect yourself first. Helping may make sense only if you could absorb the cost without putting your retirement, emergency savings or home at risk.
- There are five main options. A HELOC, a home equity loan, a home equity investment (HEI), a cash gift or a documented family loan. Each shifts the risk in a different way.
- A gift and a loan aren’t interchangeable. A gift letter must say you expect nothing back, and conventional loans don’t allow an unsecured personal loan to fund the down payment.
- The interest likely isn’t deductible. HELOC and home equity loan interest is deductible only when the money improves or buys the home that secures it, not your child’s home.
- Arizona adds two rules. Both spouses must sign to borrow against a community property home, and a gift within five years of applying for ALTCS can delay long-term care coverage.
In this Article
- Should You Use Home Equity to Help Your Adult Child Buy a House?
- Can Parents Use Home Equity to Help a Child Buy a House?
- What Are Your Options for Using Home Equity to Help?
- What Would $75,000 Cost with Each Option?
- Should the Money Be a Gift or a Loan?
- How Does Your Help Affect Your Child’s Mortgage Approval?
- Do You Owe Taxes When You Help Your Child Buy a House?
- What Are the Risks to Parents?
- When Does Using Home Equity to Help Your Child Make Sense?
- When Is It Too Risky?
- How Can You Help without Risking Your Home?
- Helping Your Child Buy a House FAQ
At a Glance: Ways Parents Can Tap Equity for a Child’s Home
| Option | Monthly Payment Impact | Borrower Debt-to-Income (DTI) | Main Risk to Parent | Best Used For |
|---|---|---|---|---|
| HELOC | Variable (Interest-only initially) | Adds to parent’s DTI | Payment shocks if interest rates rise | Flexible draw schedules or staged down payments |
| Home Equity Loan | Fixed (Principal & Interest) | Adds to parent’s DTI | Long-term monthly budget obligation | Predictable fixed-budget repayment |
| Home Equity Investment (HEI) | $0 monthly payments | No monthly debt impact | High buyout settlement cost at sale | Cash flow protection with strong home equity |
| Cash Gift (from Savings) | $0 | None | Permanently reduces retirement pool | Easiest path for child’s mortgage approval |
| Family Loan | Depends on agreed terms | Counts on child’s DTI (if declared) | Risk of unpaid personal balance | Repayment without bank interest costs |
Should You Use Home Equity to Help Your Adult Child Buy a House?
Using your own home equity is a good idea only if you can afford to lose the money. If your retirement depends on getting it back, it isn’t.
Home equity feels like free money because you don’t see it. But every option on this page either adds a payment to your budget, adds a cost when you sell, or permanently shrinks your savings. Your child has decades to recover from a money mistake. You may not.
Research backs up why so many parents do it anyway. A Federal Reserve Bank of San Francisco study found that children whose parents took equity out of their homes were 60% to 80% more likely to become homeowners. Helping works. The question is what it costs you.
How Much Equity Do Homeowners Have in Your State?
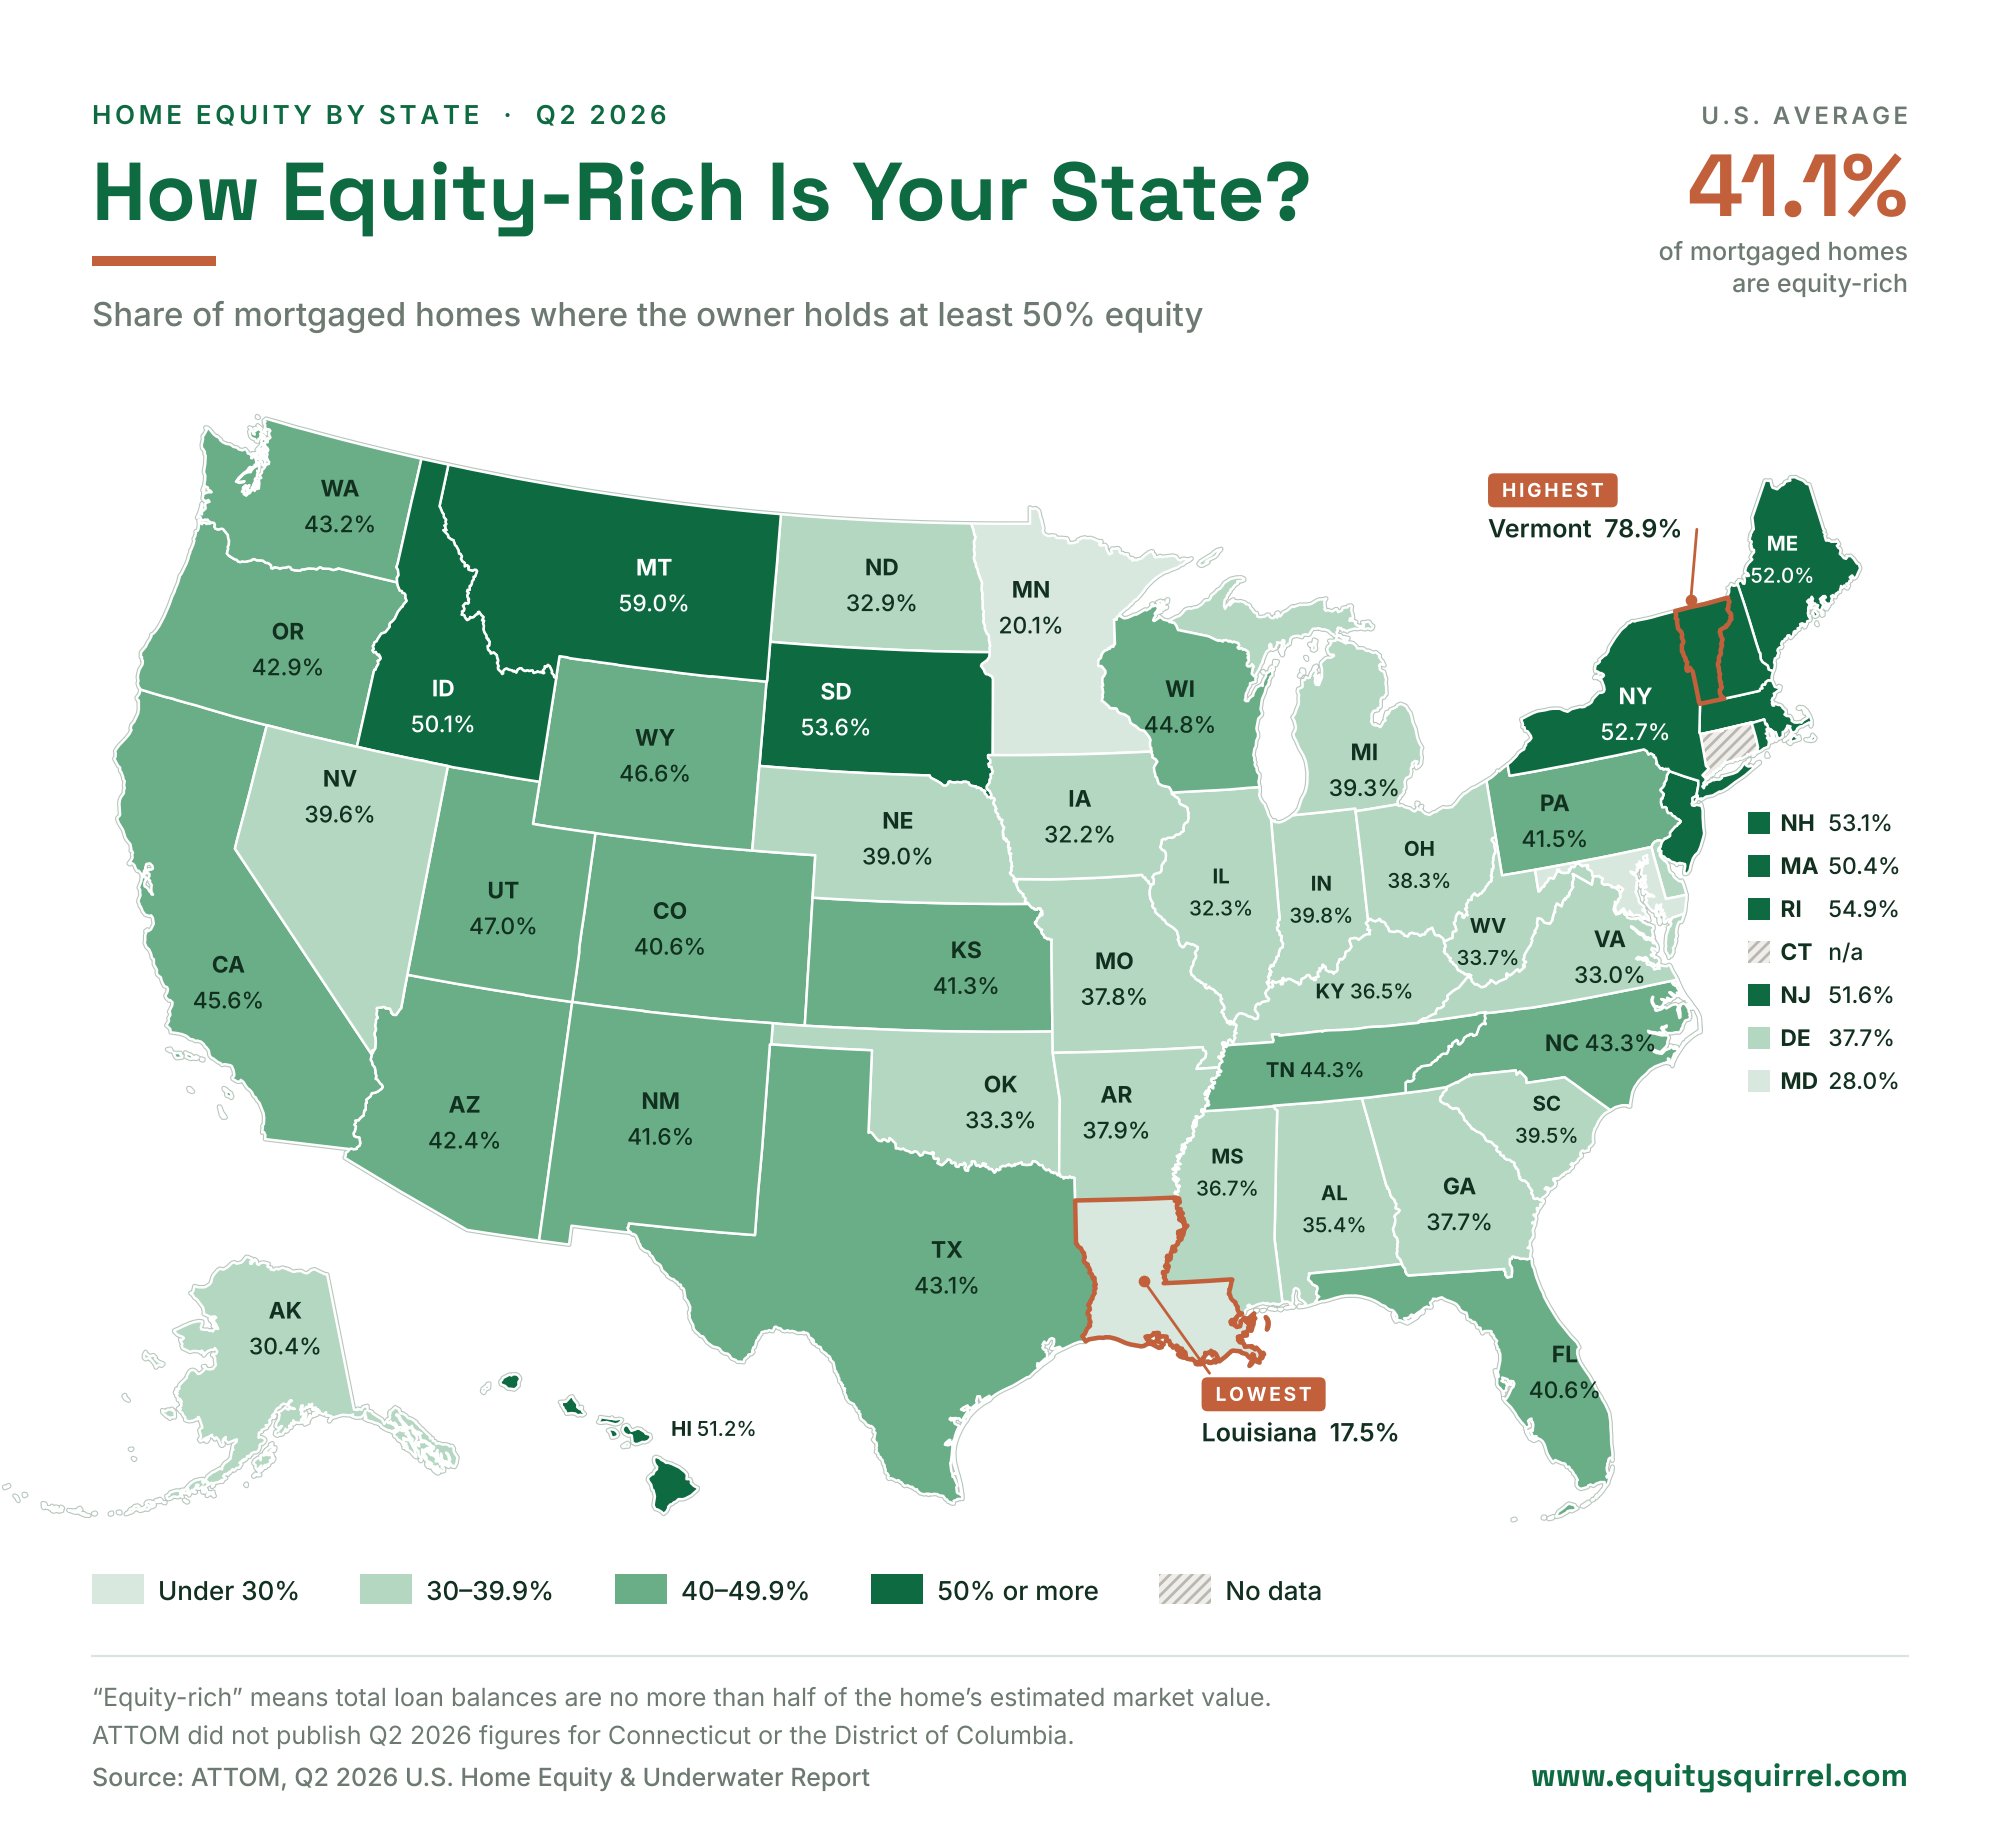
Plenty of parents have the equity to do it. In Q2 2026, 41.1% of mortgaged U.S. homes were equity-rich, meaning the owner held at least 50% equity, according to ATTOM. How much equity you have tells you what’s possible, not what you can afford to give away.
Want a real number to test against your budget? See how much cash an Unlock HEA could provide, with no monthly payments. Get Your Estimate →
Can Parents Use Home Equity to Help a Child Buy a House?
Yes. You can tap your equity with a HELOC, a home equity loan or a home equity investment, then pass the money to your child as a gift or a loan. Lenders don’t control what you do with the cash once you have it.
What they do check is you. A HELOC or home equity loan lender reviews your credit, income and debts, because you’re the one making payments. An HEI company looks mostly at your equity and credit, with no monthly payment to qualify for.
Would a new monthly payment strain your budget? Check whether you’d qualify for an Unlock HEA before you decide how to help. Check Your Eligibility →
Two things to know before you apply:
- In Arizona, both spouses usually sign. Arizona is a community property state, and A.R.S. 25-214 requires both spouses to join in any transaction that encumbers community real property. If you’re married, plan on applying together.
- Your child’s lender will look at the money too. How you pass it along (gift or loan, and how it’s documented) decides what your child’s lender will accept. That part is covered below.
A Realtor’s Take
Home prices in Phoenix and across the Sun Belt took off after COVID, and for a lot of young buyers even a starter home now feels out of reach. When parents can cover part of the down payment, the payoff compounds for years. Instead of paying rent, their kids get into the market early and start building equity of their own.
Licensed Arizona Realtor
What Are Your Options for Using Home Equity to Help?
You have five main ways to help, and the right one depends on whether you can handle a monthly payment and whether you want the money back.
Leaning toward a HELOC? See what APR you could qualify for.
The first three rows are ways to get cash from your home. The last two are ways to pass money to your child, and they can be combined with any of the first three (for example, a HELOC that funds a gift). “Family loan” payments depend on the terms you set.
A quick definition of each:
- HELOC (home equity line of credit): a revolving line secured by your home. You usually pay interest only during a draw period, often 10 years, then pay back principal and interest. The rate is usually variable.
- Home equity loan: a lump sum at a fixed rate, repaid in equal monthly payments from the start.
- Home equity investment (HEI): cash now in exchange for a share of your home’s future value. There are no monthly payments. You settle when the term ends or you sell.
- Cash gift: money you give with no expectation of repayment. It’s the easiest for your child’s lender to accept.
- Family loan: money your child agrees to pay back, ideally with a written promissory note.
Scout’s Tip
Before you sign for a HELOC, figure the payment at 2 percentage points above today’s rate. If that number would squeeze your budget, a fixed-rate home equity loan, or a smaller amount, is the safer choice. Compare current Arizona home equity rates to see where you’d start.
Featured Partners · No Monthly Payments

- Up to 30 years to settle
- Credit scores starting at ~600+
- Access up to $600,000

Home Equity Agreement (HEA)
- Use cash for anything
- 500+ credit score. No income requirements.
- Pre-qualify in under 2 minutes. No credit impact.

- Qualify in minutes. No credit impact.
- Close in as little as 3 weeks1
- Works for second homes and rentals

- Qualify in minutes
- Dedicated Investment Manager
- Access up to $600,000

- Up to 30 years to settle with MaturityMatch™
- Keep your low-rate mortgage
- Check eligibility with no credit impact
Unlock: In exchange for cash upfront, you give a share of the future value of your home. Not all homeowners will qualify. Not available in all states. Terms and conditions apply. Home Equity Agreements offered by Unlock Home Equity Solutions Inc. (NMLS #2657081).
Nada: 1“Close in as little as 3 weeks” reflects the average timeline under standard conditions. Actual timelines vary based on documentation, title, property location, and local recording or notarization requirements. Timing is not guaranteed. Terms and conditions apply. Not all homeowners will qualify. Not available in all states. Nada Loans LLC, NMLS #1993600.
What Would $75,000 Cost with Each Option?
On $75,000, a HELOC costs about $489 a month in interest at today’s average rate, a 15-year home equity loan costs about $695 a month, and an HEI costs nothing monthly but could take $135,000 or more to settle after 10 years. Here’s how each one works out.
Illustrative example only. Rates are national averages from Curinos in early November 2026: 7.83% for a HELOC and 7.50% for a home equity loan. Your rate will depend on your credit, your equity and your lender. Fees are left out.
HELOC: $75,000 at 7.83%, variable
- During the draw period: about $489 a month if you pay interest only.
- If the rate rises 2 points to 9.83%: about $614 a month, still interest only.
- When repayment starts: the payment jumps to about $619 a month at 7.83% to pay off $75,000 over 20 years. At 9.83%, it’s about $715.
- The catch: after 10 years of interest-only payments, you’d have paid about $58,700 in interest and would still owe the full $75,000.
Funding your gift with a HELOC? Compare your APR in minutes. It won’t affect your credit score.
Home equity loan: $75,000 at 7.50%, fixed for 15 years
- Payment: about $695 a month, starting right away, and it doesn’t change.
- Total interest over 15 years: about $50,100.
- After 10 years: you’d have paid about $83,400 and would still owe about $34,700.
HEI: $75,000 with no monthly payment
HEI costs depend on your home’s value when you settle, not on an interest rate. This example uses Unlock’s own published exchange rate of 1.8 (cash equal to 10% of your home’s value in exchange for 18% of its future value) on a $750,000 home, settled at the end of Unlock’s 10-year term.
Illustrative only, based on the worked example on Unlock’s cost page in November 2026. Your exchange rate depends on your offer. Unlock’s origination fee of up to 4.9% (up to $3,675 here) comes out of your cash at closing. Unlock also has an annualized cost limit that can lower the settlement if you settle early. This is not an interest rate.
Two things stand out. First, even if your home’s value never rises, you’d settle for $60,000 more than you received. Second, the settlement is due when you sell, so it comes out of the money you might be counting on to downsize or move. For how HEIs work when you buy property yourself, see using an HEI to buy another house.
What each option looks like 10 years later
Simplified comparison. It ignores fees, taxes and what your money could have earned elsewhere. Run your own numbers with our HELOC vs. HEI calculator.
Scout’s Tip
If you’re weighing an HEI because you’d rather not add a monthly payment, ask for the settlement amount in writing at 3, 5 and 10 years, at flat, 3% and 5% home value growth. Unlock publishes its exchange rate, fee and annual cost limit, which makes that comparison easier. Check your eligibility with Unlock →
Should the Money Be a Gift or a Loan?
A gift is simpler for your child’s mortgage. A loan may get your money back, but it must be documented honestly, and some mortgage types won’t accept it.
Here’s how the main loan programs treat each one:
- Conventional loans (Fannie Mae): Gifts from a relative are allowed with a signed gift letter. For a one-unit home your child will live in, the whole down payment can generally come from a gift. An unsecured personal loan can’t be used for the down payment. Borrowed money is acceptable only if it’s secured by an asset, and then the payment counts against your child’s debt-to-income ratio.
- FHA loans: Family members can lend the down payment, secured or unsecured. If you borrowed the money yourself (for example, from your HELOC), the lender will ask you to document where it came from.
Never call a loan a gift. A gift letter states that no repayment is expected. If you plan to be paid back, signing one is a false statement on a mortgage application. Pick one and paper it correctly.
If you choose a family loan:
- Write a promissory note with the amount, rate, payment schedule and what happens if your child can’t pay.
- Consider charging at least the IRS minimum rate, called the applicable federal rate (AFR). The IRS publishes it monthly. In November 2026, the short-term AFR (loans of three years or less) was 4.67%.
- Know the $100,000 rule. For family loans of $100,000 or less in total, the IRS limits any interest it treats you as earning to your child’s net investment income for the year. If that income is $1,000 or less, it’s treated as zero. A tax professional can confirm how this applies to you.
- Remember your own loan doesn’t pause. If your child stops paying you, you still owe your HELOC or home equity loan.
Weighing a home equity investment so you don’t add a monthly payment? See what an Unlock home equity agreement (HEA) could offer before you compare the costs below. See What You Could Get →
How Does Your Help Affect Your Child’s Mortgage Approval?
A gift doesn’t add any debt for your child, so it usually helps their approval. A family loan with a payment can count against their debt-to-income ratio (DTI), which may reduce how much they can borrow.
- Cash gift: no payment for your child, so no DTI impact. It needs a gift letter and proof of transfer.
- Family loan: where the program allows it, the monthly payment is counted in your child’s DTI.
- Your HELOC or home equity loan: it’s your debt, not your child’s, so it doesn’t appear on your child’s credit report. On an FHA loan, the lender may still ask you to show the source of the funds.
- Your HEI: it’s an agreement on your home, with no payment and nothing on your child’s application beyond documenting the gift or loan.
Do You Owe Taxes When You Help Your Child Buy a House?
Probably not, but you may need to file a gift tax return. In 2026, each parent can give up to $19,000 to any one person without filing. Above that, you file IRS Form 709, and the excess reduces your $15 million lifetime exemption. Actual gift tax is rare.
What that means in real numbers for a $75,000 gift:
- One parent giving to one child: $19,000 is covered by the annual exclusion. The other $56,000 is reported on Form 709.
- Two parents giving to one child: $38,000 is covered. The other $37,000 is reported.
- Two parents giving to a married child and their spouse: each parent can give $19,000 to each of them, which covers $76,000. Check with the lender first, because a gift to a spouse who isn’t on the mortgage can need extra documents.
The interest probably isn’t deductible. IRS Publication 936 says home equity loan and HELOC interest is deductible only when the money is used to buy, build or substantially improve the home that secures the loan. Your child’s house isn’t that home. The One Big Beautiful Bill Act made this rule permanent.
Ask a CPA before you give, especially if your community property or estate plan is involved.
What Are the Risks to Parents?
The biggest risk is that your home secures money you’ve given away. If your income drops or the payment rises, it’s your house on the line, not your child’s.
- Your home is the collateral. Missing HELOC or home equity loan payments can lead to foreclosure, no matter what happens to your child’s house.
- HELOC payments can rise twice. Once if rates go up, and again when the interest-only period ends. In our example, $489 becomes $619 at the same rate.
- Less cushion for emergencies. Equity you’ve used isn’t available for a roof, a health event or a market downturn.
- The timeline outlasts your plans. A HELOC with a 10-year draw and 20-year repayment runs 30 years. If you’re 65 when you open it, it could run until you’re 95.
- An HEI can be expensive to settle. In our example, it costs $60,000 more than you received even in a flat market, and more if your home’s value grows.
- Moving or refinancing gets harder. A HELOC or home equity loan must be paid off when you sell. An HEI settles when you sell. Either way, that money comes out of your next home’s budget. See how an HEI lien affects your home.
- Long-term care in Arizona. Arizona’s long-term care program, ALTCS, looks back 60 months at gifts and transfers made for less than fair value. A gift in that window can create a penalty period with no long-term care coverage. The federal gift tax exclusion doesn’t protect you from it.
- Family risk. If a family loan isn’t repaid, or your child’s marriage ends, the money may not come back. Ask an attorney how a gift to a married child should be structured.
When Does Using Home Equity to Help Your Child Make Sense?
It makes sense when the help is affordable for you even in a bad year. Run through this list. If you can say yes to every item, home equity is a reasonable source.
- You’d still have several months of emergency savings afterward.
- Your retirement plan works even if the money never comes back.
- You could make the HELOC payment from your income even if the rate rose 2 points, or you’d use a fixed-rate loan.
- You plan to stay in your home, or you’d have enough left to move after paying off the debt or settling the HEI.
- Your spouse agrees (and in Arizona, will co-sign).
- Your child can afford the mortgage on their own income. Your help reduces the down payment, not the monthly payment they can carry.
- You’ve decided gift or loan, and you’ll document it correctly.
Featured Partners · No Monthly Payments
- Up to 30 years to settle
- Credit scores starting at ~600+
- Access up to $600,000
Home Equity Agreement (HEA)
- Use cash for anything
- 500+ credit score. No income requirements.
- Pre-qualify in under 2 minutes. No credit impact.
- Qualify in minutes. No credit impact.
- Close in as little as 3 weeks1
- Works for second homes and rentals
- Qualify in minutes
- Dedicated Investment Manager
- Access up to $600,000
- Up to 30 years to settle with MaturityMatch™
- Keep your low-rate mortgage
- Check eligibility with no credit impact
Unlock: In exchange for cash upfront, you give a share of the future value of your home. Not all homeowners will qualify. Not available in all states. Terms and conditions apply. Home Equity Agreements offered by Unlock Home Equity Solutions Inc. (NMLS #2657081).
Nada: 1“Close in as little as 3 weeks” reflects the average timeline under standard conditions. Actual timelines vary based on documentation, title, property location, and local recording or notarization requirements. Timing is not guaranteed. Terms and conditions apply. Not all homeowners will qualify. Not available in all states. Nada Loans LLC, NMLS #1993600.
When Is It Too Risky?
It’s too risky when helping your child would make your own finances fragile. Hold off if any of these apply:
- Your paychecks will stop before the debt is paid off, and you don’t have another way to make the payment.
- You’d be using most of your equity, leaving little room if home values fall.
- You’re relying on the money coming back to pay your own bills.
- You expect to need long-term care within five years.
- Your child could only qualify with your help and would be stretched by the monthly mortgage.
- You’d only consider an HEI because you couldn’t handle any monthly payment. That’s a sign to ask whether you can afford to give this money at all.
How Can You Help without Risking Your Home?
You can help without borrowing against your house by giving a smaller amount from savings, pointing your child to down payment assistance, or helping in ways that don’t involve a lump sum.
- Give a smaller gift from savings. Even $10,000 to $20,000 can cover closing costs or round out a down payment, with no debt on your home.
- Pair your help with Arizona down payment assistance. The Arizona Industrial Development Authority’s Home Plus program offers up to 4% in down payment and closing cost help as a forgivable second loan. It isn’t limited to first-time buyers, and it has an income limit. Your child applies through an approved lender.
- Co-sign or join the loan. Fannie Mae allows a parent to be a non-occupant co-borrower. Your home isn’t pledged, but you’re fully responsible for the mortgage, and it counts against your own borrowing.
- Let your child live with you to save. A year or two of lower rent can build a down payment without touching your equity.
- Lend from savings, not your house. A documented family loan funded from savings puts less at risk than one funded with a HELOC.
If you still decide home equity is the right source, compare offers, start with the smallest amount that works, and read up on how much equity you need for an HEI or what to expect if you settle an HEI early.
Helping Your Child Buy a House FAQ
Yes. A HELOC is your debt, and you can give the cash as a gift with a signed gift letter. Your child’s lender will want proof of where the money came from, and on an FHA loan you may need to document your HELOC. You’re responsible for the payments, even if your child’s circumstances change.
Sometimes. FHA allows family loans, secured or unsecured. Conventional loans don’t allow an unsecured personal loan to fund the down payment. Either way, never sign a gift letter for money you expect to get back.
In 2026, $19,000 per parent, per recipient. Two parents can give $38,000 to one child, or $76,000 if they also give to the child’s spouse. Above that, you file Form 709, but you likely won’t owe gift tax.
Generally no. HELOC and home equity loan interest is deductible only when the money buys, builds or substantially improves the home that secures the loan. That’s your home, not your child’s.
No. It’s your debt, so it’s on your credit, not your child’s. Your child’s lender may still ask for documents showing where the gift came from.
Yes. An HEI gives you cash with no monthly payment in exchange for a share of your home’s future value. It can be expensive: in our example, $75,000 settles for $135,000 after 10 years even if the home’s value stays flat.
It’s an option that keeps your home from being pledged, but you’d be fully responsible for the mortgage if your child can’t pay, and it counts against your own borrowing.
How We Checked This Article. Last reviewed: November 2026. We checked the 2026 NAR Profile of Home Buyers and Sellers for first-time buyer data; Fannie Mae’s Selling Guide on gifts, borrowed funds and non-occupant borrowers; HUD’s FHA guidance on family loans; IRS Publication 936, Rev. Proc. 2025-32 and Rev. Rul. 2026-21 for tax figures; A.R.S. 25-214; AHCCCS’s eligibility manual on the ALTCS look-back; and the Arizona IDA’s Home Plus materials. Rates are Curinos national averages from November 2026. The HEI example uses Unlock’s published cost page. Payments were calculated with standard amortization formulas. We’ve asked Unlock to confirm how its annualized cost limit is applied and will add its answer here with the date we received it.
This article is not tax or legal advice. Talk to a tax professional about gift tax and family loans, and to an elder law attorney about ALTCS planning. EquitySquirrel is an educational resource operated by Scout Media LLC, not a lender or HEI provider. This content does not constitute financial, legal, or investment advice. HEI terms vary by provider and are subject to change; confirm current terms directly. Consult a licensed financial professional before making decisions about your home equity. Aleksandra Kadzielawski, Lic #SA694336000.